Back
 All articles
Approximately 60% of alcohol consumed in Kenya is illicit, representing an estimated KES 203 billion in sales and KES 120 billion in annual government fiscal losses, according to the Alcoholic Beverages Association of Kenya (ABAK). These figures reveal a challenge that goes beyond lost tax revenue. For the Africa beverage market, understanding it means looking beyond headline growth figures, down to the realities shaping what consumers buy, what they can afford, how products reach them and which competitors they encounter.
Yet Kenya’s experience is not representative of the entire continent. According to The New Pour Report 2026, illicit alcohol accounts for 18% of the market in South Africa and 12.9% in Zambia, compared with a 12-country average of 8.3%. The differences underline why Africa’s beverage markets cannot be approached as one uniform opportunity.
Published by Drinkabl Africa, The New Pour Report 2026 examines the forces shaping the continent’s beverage industry, from investment and emerging categories to consumer behaviour and market-specific challenges.
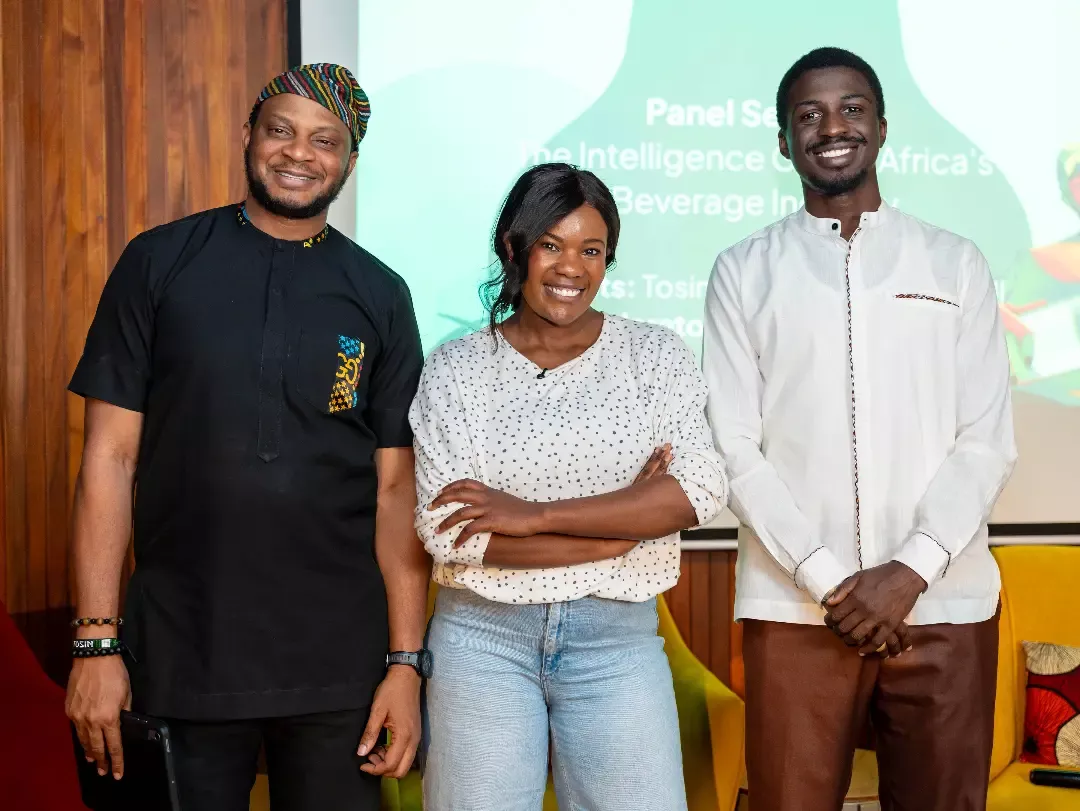
LOOKA Research attended the first New Pour Summit and later partnered with Drinkabl to host the Nairobi edition of New Pour Exclusives, bringing industry stakeholders together to discuss the report’s insights and what they mean for the beverage sector.
What the Report Reveals About Africa’s Beverage Opportunity
1. A market attracting serious investment
Drinkabl projects that Africa’s alcoholic drinks market will reach $130.8 billion by 2029, growing at a compound annual growth rate of 7.35%. The report also highlights $4.9 billion in major transactions: Coca-Cola HBC’s acquisition of a 75% stake in Coca-Cola Beverages Africa for $2.6 billion, and Asahi Group’s $2.3 billion acquisition of Diageo’s 65% stake in East African Breweries.
These investments signal confidence in the continent’s long-term potential. But the scale of the opportunity does not remove the need to understand the conditions within individual markets.
2. Growth extends beyond alcohol
The beverage opportunity is not limited to alcoholic drinks. The report puts Africa’s non-alcoholic beverage revenue at $124 billion in 2025 and highlights developments across coffee, tea, alcohol-free beverages and ready-to-drink products.
It also identifies trends including premiumisation, changing flavour preferences and growing interest in alcohol-free options. For brands, these shifts create opportunities to rethink product portfolios and respond to different consumer needs and occasions. Understanding which trends matter most, however, requires looking at the audiences and markets behind them.
3. Market opportunity comes with local complexities
Kenya’s illicit alcohol figures offer a striking example of how market conditions can complicate the growth story. The estimated KES 203 billion in illicit alcohol sales and KES 120 billion in annual fiscal losses illustrate the scale of the challenge.
The report also points to affordability pressures, illicit competition and differences in market structure across countries. These factors matter when businesses assess market size, pricing, distribution and potential returns. The lesson is not that every African market faces the same challenges at the same scale. It is that understanding local realities is essential to making informed decisions.
4. Africa cannot be treated as one market
Drinkabl’s report highlights distinct category preferences across countries. Spirits dominate in Nigeria and Kenya, wine leads consumer preference in Morocco and Tanzania, while cider has a strong position in South Africa. Beer remains the continent’s leading alcohol category overall, accounting for 26% of recent consumption in the report.
These differences have practical implications for product development, brand positioning and route-to-market strategies. A successful approach in one country may not translate directly to another. For businesses expanding across Africa, market-specific intelligence helps replace broad assumptions with a clearer understanding of local consumers and competitive conditions.
Taking the Research Beyond the Report
The Nairobi New Pour Exclusives conversation reflected the value of bringing industry intelligence into a room where stakeholders can consider its implications. Through its engagement with Drinkabl, LOOKA contributed to extending the discussion beyond the report itself. Africa’s beverage industry presents significant potential, but capturing it requires more than recognising a growing market. Explore The New Pour Report 2026 for the findings, trends and market insights informing this conversation.